Homeowner’s insurance often does help pay for a roof replacement, but only when the damage comes from a sudden and covered event. This matters because your roof is one of the biggest protections your home has, and repairs or a full replacement can feel overwhelming without support.
Knowing how coverage works helps you act quickly and avoid paying more than you should out of pocket. For homeowners in coastal regions where powerful storms are a fact of life, this knowledge is especially valuable. Learn about what insurance covers, how to file a claim, and how you protect your home.
Does Homeowner’s Insurance Cover Roof Replacement?
Yes, most policies cover roof replacement when the damage results from a covered peril rather than age or neglect. Insurance is designed to protect you against sudden events, not slow wear and tear over time.
While a roof damaged by a winter storm or falling tree is usually eligible, a roof that simply reached the end of its lifespan often is not. Your policy may pay actual cash value or full replacement cost, so it helps to read your coverage closely. Understanding this difference sets you up for a smoother claim.
What Types of Roof Damage Are Covered by Insurance?
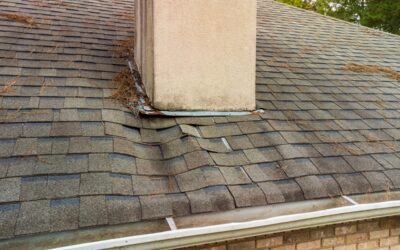
Insurance typically covers roof damage caused by sudden, unexpected events common to New England weather. In Massachusetts, wind and ice cause many of the claims we see each year. The most commonly covered issues include the following:
- Wind and storm damage: High winds can lift or tear off shingles, leaving your home exposed to leaks.
- Ice dam damage: Freezing and thawing can force water under the roof and into your ceilings and walls.
- Falling objects: Tree limbs and heavy debris during a storm often qualify for a claim.
- Hail impact: Hail can bruise or crack shingles and shorten the life of your roof.
Damage from a lack of maintenance is rarely covered, which is why routine roof inspection work is so important.
How Do I File a Roof Insurance Claim?
Start by documenting the damage as soon as it is safe to do so. A clear record gives your claim the strongest chance of approval. We recommend following a simple process to keep things organized:
- Take photos and notes of all visible damage inside and outside your home.
- Contact your insurance provider to report the loss and open a claim.
- Schedule a professional roof repair assessment to confirm the extent of the problem.
- Meet the adjuster on site so nothing gets overlooked.
Having an experienced contractor present during the inspection often helps you get a fair outcome. At Giannini Roofing, we’re happy to handle the insurance’s nuances and adjustor communication for you.
Should I Repair or Replace My Roof After Storm Damage?
The right choice depends on the age of your roof and how widespread the damage is. Minor issues like a few missing shingles may only call for a targeted repair. Larger problems, such as damage across multiple sections, usually point toward a full roof replacement for lasting protection.
We often guide homeowners through this decision by weighing repair costs against long-term value. A complete roofing system can also boost curb appeal and improve energy efficiency for years to come.
Expert Roof Repair and Replacement Across Plymouth County and the South Shore
At Giannini Roofing, we bring years of local experience to every roof repair and roof replacement we handle. As a family-owned team serving Whitman, Abington, Rockland, Cohasset, and the surrounding South Shore communities, we know how our storms affect your home. We also help you navigate the insurance process so you feel confident from start to finish. To learn more and get started today, contact us online or give us a call at (781) 351-1785